Australian eCommerce Statistics 2026: Market Size, Growth Trends & Consumer Insights

Australian eCommerce Statistics


Australian eCommerce is no longer an emerging channel. It is a core part of how retail operates, how consumers discover products and how businesses compete for revenue.


Digital access is effectively universal. In 2025, 99.7% of Australian adults used the internet, while 97% accessed it using a mobile phone and 92% used mobile internet every day.


Australians also accessed the internet through an average of 4.1 devices, reinforcing how fragmented the path from product discovery to purchase has become.


The scale of eCommerce reflects that shift. Australians spent $82.6 billion online in 2025, up 14% year-on-year, with online purchases accounting for approximately 24% of retail spending.


Around 9.8 million households, or 82% of Australian households, made an online purchase during the year.


Growth is therefore no longer primarily about convincing Australians to shop online. Most already do.


The opportunity is increasingly about how frequently they purchase, where they discover products, which retailers capture that demand and how effectively businesses convert it into revenue.


Latest Australian eCommerce Statistics for 2026


The latest 2026 data suggests Australian eCommerce is still expanding, but the way consumers are spending is changing.


Australia Post reported that Australians spent $21.9 billion online during the final quarter of FY26.


At the same time:


  • The average online basket fell to a record-low $90

  • 59% of shoppers say they never buy at full price anymore

  • Marketplaces accounted for 42% of online transactions

  • Marketplace transactions increased 17% year-on-year


This points to an important shift.


Australians have not stopped shopping online. Instead, they are becoming more selective, making smaller purchases and looking harder for value.


Separate 2026 data from Adobe Digital Insights reinforces the broader growth trend. Australian consumers spent $39.3 billion online between January and July 2026, up 8.6% from the same period in 2025.


These datasets use different methodologies and should not be treated as directly interchangeable. However, they point in the same direction: Australian eCommerce continues to grow while purchasing behaviour becomes increasingly price-sensitive, frequent and marketplace-driven.


Market Size and Growth


Australian eCommerce recorded another substantial increase in 2025.


According to Australia Post and CommBank iQ data, Australians spent $82.6 billion online in 2025, up from $72.5 billion in 2024.


That represents annual growth of approximately 14%.


Online spending also accounted for around 24% of total retail expenditure, meaning close to one in every four retail dollars measured by this dataset was spent online.


But growth was not driven solely by larger orders.


The average online basket actually declined to $96, while Australians made more purchases throughout the year. Australia Post reported shoppers made four more online purchases on average than in the previous year.


This suggests the market is becoming increasingly high-frequency rather than simply high-ticket.


Participation reached a record level as well. Around 9.8 million Australian households shopped online during 2025, equivalent to 82% of households.


Marketix Digital's own analysis of these figures provides another way of understanding the scale.


Dividing Australia's $82.6 billion in online expenditure across 9.8 million participating households implies approximately $8,429 in online spending per participating household during 2025.


The available figures also imply approximately 88 online purchases per participating household over the year.


These are estimates derived from national spending and participation data rather than directly reported household averages, but they illustrate how deeply online purchasing is now embedded in household consumption.


Why Australian eCommerce Figures Sometimes Differ


Not every published estimate of Australian online retail measures the same thing.
Australia Post, CommBank iQ, the Australian Bureau of Statistics and NAB use different datasets, definitions, coverage and reporting periods.


For example, Australia Post estimates online spending represented approximately 24% of retail expenditure in 2025, while the ABS reported a considerably lower online share under its narrower Retail Trade methodology.


The figures should therefore be treated as separate indicators of Australian online retail activity rather than competing measurements of an identical market.


For businesses, the more important signal is the direction shared across the datasets: online purchasing is now a substantial, recurring component of Australian retail activity.


The commercial opportunity is therefore no longer simply to participate in eCommerce. It is to capture a greater share of an already large and competitive market.


Australian Online Shopping Behaviour


Adoption is no longer the main story. Frequency, value sensitivity and retailer choice are.
 

A record 82% of Australian households shopped online in 2025, representing approximately 9.8 million households.


Online purchasing is also becoming increasingly habitual.


Around 41% of participating households purchased online at least once a fortnight, while 35% of online shoppers now buy online at least weekly.


Among Millennials, the weekly purchasing rate rises to 47%.


But greater purchasing frequency does not necessarily mean customers have become easier to win.


Australian consumers remain highly value-conscious. Australia Post found that 81% of shoppers actively shop around for the best deals.


Separate research from IAB Australia found that 72% of consumers were cutting back on non-essential purchases.


The result is a customer who shops frequently but compares more carefully.


Loyalty is becoming more fragmented as well.


The average Australian household now shops across approximately 16 different retailers each year, more than double the number recorded around a decade ago.


That changes the competitive environment significantly.


Retailers are no longer competing only to acquire customers. They are repeatedly competing to win the next purchase.


For eCommerce businesses, this raises the importance of:


  • Competitive pricing and promotional strategy

  • Clear product differentiation

  • Reviews and other trust signals

  • Delivery certainty

  • Strong return policies

  • Easy product comparison

  • Customer retention

  • Fast, low-friction purchasing


More online demand creates opportunity, but it also gives consumers more opportunities to compare retailers before deciding where to spend.


Device Usage and Payment Trends


Device Usage and Payment Trends


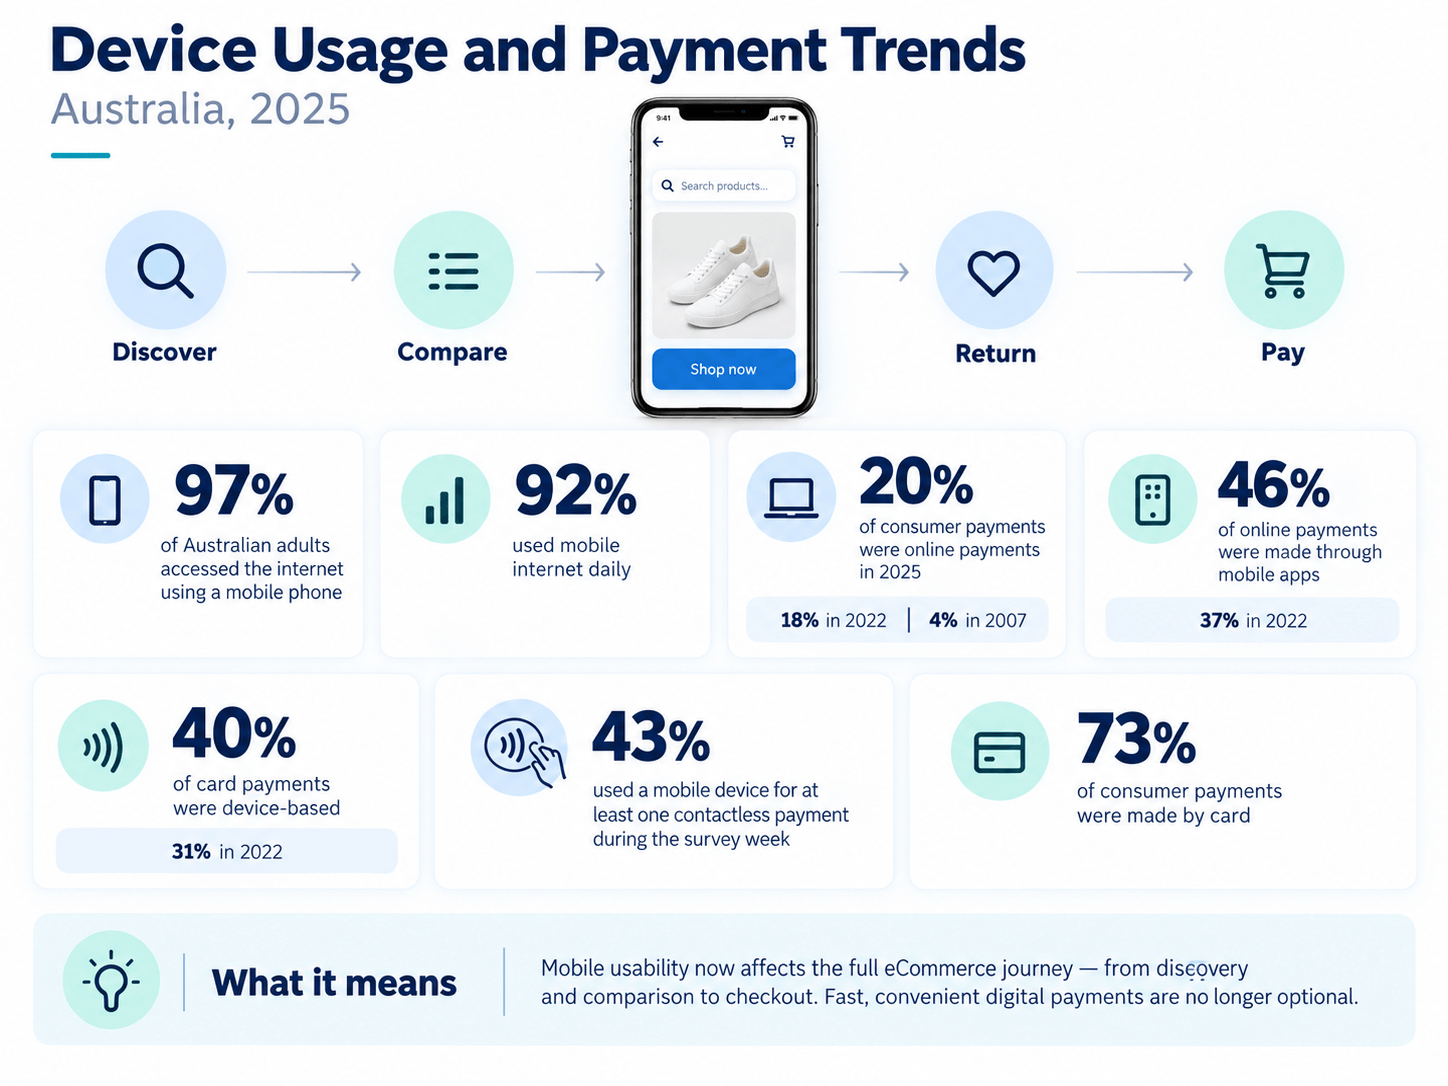
Mobile is now embedded throughout the Australian purchase journey, from discovery and comparison through to payment.


In 2025, 97% of Australian adults accessed the internet using a mobile phone and 92% used mobile internet daily.


Payment behaviour is moving in the same direction.


According to the Reserve Bank of Australia's 2025 Consumer Payments Survey, online payments accounted for approximately 20% of consumer payments in 2025, up from 18% in 2022 and only 4% in 2007.


Mobile and app-based transactions are becoming particularly important.


Payments made through mobile apps accounted for approximately 46% of online payments in 2025, up from 37% in 2022.


Mobile wallets have also continued to spread across the broader payments market. Device-based payments represented around 40% of card payments, compared with 31% in 2022, while 43% of consumers used a mobile device to make at least one contactless payment during the RBA's survey week.


Cards remain the dominant overall payment method, accounting for approximately 73% of consumer payments, although that figure includes both online and offline transactions.
The distinction matters.


General card statistics should not be treated as eCommerce checkout statistics, but they do demonstrate the broader consumer expectation for fast and convenient digital payments.
For online retailers, this makes mobile usability a commercial requirement rather than simply a design consideration.


A customer may discover a product, compare alternatives, return to the site and complete the purchase entirely from the same mobile device.


Any friction in that process can weaken the value of the traffic that was acquired in the first place.


That is also where structured approaches such as eCommerce SEO need to extend beyond rankings alone. Capturing search demand creates the opportunity; the website still needs to turn that demand into revenue.


Marketplaces and the Competitive Landscape


Marketplaces have become a structural part of Australian eCommerce.


Australians spent $18.9 billion through pure online marketplaces in 2025, up approximately 13% year-on-year and equivalent to around 23% of total online spending.


Their share of transaction volume is even larger.


By the final quarter of FY26, 42% of Australian online transactions were occurring through marketplaces, with marketplace transaction volume growing 17% year-on-year.


Individual platforms are expanding rapidly.


Roy Morgan found that Temu reached 5 million Australian shoppers in 2025 while Shein reached 2.9 million. Their shopper numbers increased approximately 17% and 28% respectively during the year.


Amazon added another 500,000 shoppers, an increase of approximately 6%.


Roy Morgan estimates that Amazon, Temu and Shein generated close to $12 billion in Australian retail sales combined during 2025, more than $2 billion above the previous year's estimate.


That matters beyond the platforms themselves.


Global marketplaces influence the prices, delivery standards, product ranges and purchasing experiences consumers begin to expect from other retailers.


Australia Post found marketplace apps are now used by 69% of shoppers, approaching the 78% who use retailer websites.


For independent retailers, competing directly with marketplaces on range or lowest price may not always be realistic.


Differentiation therefore becomes more important through factors such as:


  • Specialist expertise

  • Exclusive products

  • Product quality

  • Brand trust

  • Better advice and product information

  • Faster or more reliable fulfilment

  • Customer service

  • Loyalty and retention


The competitive landscape is no longer purely retailer against retailer.


Australian businesses increasingly compete against marketplaces, retailer websites, social platforms, search engines and emerging AI discovery channels simultaneously.


Product Discovery and the Purchase Journey


Australian Ecommerce Discovery Journey


The path from discovery to purchase has become more fragmented.


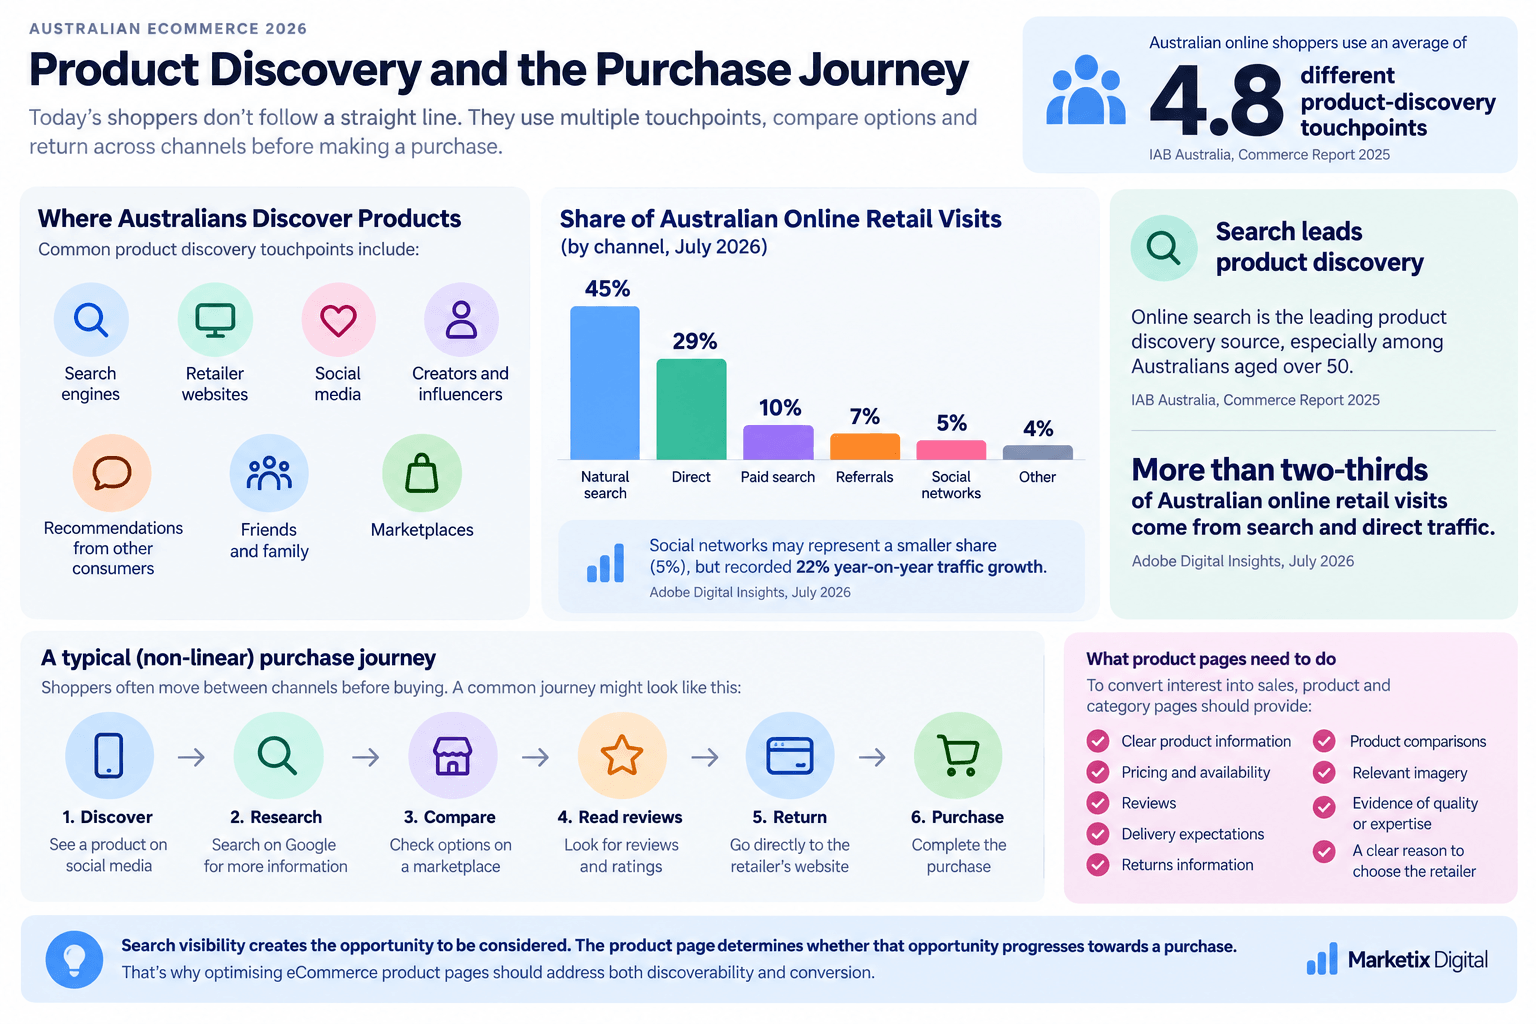
Australian online shoppers use an average of 4.8 different product-discovery touchpoints, according to IAB Australia's Commerce Report.


Those touchpoints can include:


  • Search engines

  • Retailer websites

  • Social media

  • Creators and influencers

  • Recommendations from other consumers

  • Friends and family

  • Marketplaces


Search remains particularly important.


IAB found online search was the leading overall product discovery source, especially among consumers aged over 50.


Newer 2026 retail traffic data reinforces its role.


Adobe Digital Insights found that natural search generated approximately 45% of Australian online retail visits, while direct traffic accounted for 29%.


Together, those channels generated more than two-thirds of measured retail visits.


Social networks represented a smaller 5% share but recorded 22% year-on-year traffic growth, indicating that the discovery landscape is continuing to diversify.


This creates an important distinction for retailers.


A customer's first interaction with a product is not necessarily the interaction that produces the sale.


Someone may discover a brand on social media, research the product through Google, compare alternatives on a marketplace, read reviews and then return directly to complete the purchase.


Search therefore functions as both a discovery channel and a validation channel.


For eCommerce businesses, product and category pages increasingly need to do more than rank.


They need to help consumers make a decision.


That means providing:


  • Clear product information

  • Pricing and availability

  • Reviews

  • Delivery expectations

  • Returns information

  • Product comparisons

  • Relevant imagery

  • Evidence of quality or expertise

  • A clear reason to choose the retailer


This is why optimising eCommerce product pages should address both discoverability and conversion. Search visibility creates the opportunity to be considered; the page itself determines whether that opportunity progresses towards a purchase.


AI Is Becoming a Product Discovery Channel


AI is beginning to influence how Australians research products.


Australia Post found that 62% of Australian shoppers use AI, while 32% already use it for shopping advice.


Half believe AI will eventually be used for online shopping.


Traffic data suggests that behaviour is beginning to translate into retailer visits.


Adobe Digital Insights reported that AI-driven traffic to Australian retail websites increased 108% year-on-year in July 2026.


Traditional channels remain much larger, natural search alone accounted for 45% of retail traffic in Adobe's dataset, but the rate of growth highlights how quickly discovery behaviour can change.


The next development is agentic commerce, where AI systems move beyond recommending products and begin assisting with or completing transactions.


Consumer enthusiasm remains more cautious than business enthusiasm.


Australia Post found:


  • 44% of Australian businesses advocate agentic commerce

  • Only 16% of shoppers currently share that enthusiasm

  • 85% of businesses are taking steps to prepare for agent-led purchasing


The gap matters.


AI commerce may become commercially significant, but businesses should distinguish between technology adoption and actual consumer demand.


For retailers preparing for AI-led discovery, the immediate priorities are practical.


Product information should clearly communicate price, availability, specifications, delivery, returns and use cases in formats that both humans and machines can interpret.


Search visibility is therefore beginning to expand beyond traditional search engines into a wider search and discovery ecosystem.


Delivery Has Become Part of the Conversion Experience


The eCommerce experience does not end at checkout.
 

Delivery options can influence whether the checkout happens at all.


Australia Post found that 69% of Australian shoppers want a range of delivery options at checkout, including out-of-home collection options such as Parcel Lockers.


When an order is urgent, 26% expect same-day or next-day delivery.


Delivery quality also affects repeat purchasing.


Approximately 73% of shoppers say a good delivery experience makes them more likely to buy online.


Conversely, 70% say poor delivery communication at checkout reduces their likelihood of completing a purchase.


That makes fulfilment part of conversion optimisation.


Before purchasing, consumers increasingly want to know:


  • How much delivery costs

  • When the order will arrive

  • Whether express delivery is available

  • Whether they can collect the order

  • How returns work

  • Whether tracking is available


For retailers, improving these areas can strengthen both initial conversion and customer retention.


When the average Australian household already shops across approximately 16 retailers per year, a reliable delivery experience can become one of the reasons a customer returns rather than choosing another store next time.


Australian eCommerce Website Performance


High online demand does not automatically mean Australian retailers deliver strong digital experiences.


Marketix Digital analysed 50 Australian-facing transactional eCommerce websites across 13 retail categories using mobile real-user data from Google's Chrome UX Report.


The research found that only 16% of the websites analysed passed all three mobile Core Web Vitals.


The results were:


  • 60% achieved a good Largest Contentful Paint result

  • 20% achieved a good Interaction to Next Paint result

  • 56% achieved a good Cumulative Layout Shift result

  • Only 16% passed all three Core Web Vitals simultaneously


Interaction responsiveness was the most common problem.


The median Interaction to Next Paint across the sample was 308 milliseconds, above Google's 200-millisecond threshold for a good result.


By comparison, median Largest Contentful Paint was 2,310 milliseconds and median Cumulative Layout Shift was 0.08, both within Google's good thresholds.


This does not prove that slower websites generated fewer sales. The benchmark did not have access to retailer-level conversion or revenue data.


What it does show is that strong eCommerce demand can coexist with significant room for improvement in digital execution.


Approximately five in every six websites in the sample failed at least one Core Web Vital.


For retailers, market growth and website performance should therefore be assessed separately.


Demand indicates the size of the opportunity.


Website performance influences how effectively a business is positioned to serve that demand once visitors arrive.

Read the full Australian eCommerce Performance Report 2026.


Risk, Trust, and Security


As more purchasing moves through digital channels, payment security remains an important part of the eCommerce environment.


Card-not-present fraud, which includes fraud involving remote card transactions, reached $816 million in Australia during 2024, an increase of 19%.


It accounted for approximately 90% of all card-payment fraud.


However, the underlying picture is more nuanced than simply saying online fraud is worsening.


The domestic card-not-present fraud rate actually declined to a record low of 97 cents for every $1,000 spent.


A large proportion of the overall increase came from overseas transactions. Although Australian cards used overseas represented only around 3% of card spending, overseas card-not-present activity accounted for approximately half of all card fraud.


At the consumer level, the problem remains substantial.


The Australian Bureau of Statistics found that approximately 2.3 million Australians experienced card fraud during 2024–25, equivalent to around 10% of people aged 15 and over.


For the most recent card-fraud incident:


  • 90% had money withdrawn or used

  • The median amount involved was $250

  • 75% received some reimbursement

  • 72% were fully reimbursed


The ABS estimated the gross value withdrawn or used across affected consumers at $2.2 billion, falling to an estimated $350 million in net losses after reimbursements.


For retailers, trust therefore remains commercially important.


Consumers are being asked to provide payment and personal information in an environment where fraud awareness is high.


Visible signals such as secure payment processing, recognisable payment methods, clear delivery and returns policies, authentic reviews and transparent business information can reduce unnecessary uncertainty during the purchase process.


Trust is not simply a branding consideration.


In eCommerce, it can directly affect whether a customer is comfortable completing the transaction.


What the Statistics Mean for Australian eCommerce Businesses


The data describes a large eCommerce market that is continuing to grow but becoming harder to compete in.


Several patterns stand out.


Consumers are buying more frequently


Online spending reached $82.6 billion in 2025 even though average basket size declined.
The growth therefore appears to be increasingly driven by frequent purchasing across millions of households, rather than simply larger transactions.


Customers are more price-sensitive


More than eight in ten shoppers actively compare deals, while 59% now say they never pay full price.


Retailers need to communicate value clearly without assuming that discounting alone is a sustainable competitive strategy.


Marketplaces are capturing more purchasing activity


Marketplaces now represent 42% of online transactions.


Businesses therefore need to decide where marketplaces fit within their acquisition strategy while still building direct customer relationships that reduce dependence on third-party platforms.


Search remains central to product discovery


Natural search represented 45% of retail visits in Adobe's 2026 dataset.


Despite the growth of social media and AI discovery, search remains one of the strongest channels connecting product research with commercial intent.


For businesses investing in organic acquisition, an eCommerce SEO ROI calculator can help translate search visibility into potential commercial value rather than treating rankings as the end objective.


Discovery is becoming more fragmented


Consumers use an average of 4.8 discovery touchpoints.


The business that receives the first interaction may not ultimately receive the sale.


Retailers therefore need consistency across search, product pages, marketplaces, social content, reviews and direct traffic.


AI is emerging alongside traditional search


AI-driven retail traffic remains much smaller than established channels, but its rapid growth makes it difficult to ignore.


Product information increasingly needs to be structured for both human consumers and machine-led discovery.


Mobile experience matters after the click


Nearly all Australian adults access the internet through mobile phones, yet Marketix's benchmark found only 20% of sampled eCommerce websites achieved a good mobile INP result.


Acquiring traffic is therefore only part of the commercial problem.


Retailers also need to ensure their websites can efficiently serve and convert that demand.


Delivery can influence conversion


Customers increasingly expect delivery cost, timing and options to be clear before they purchase.


Fulfilment should therefore be treated as part of the customer experience rather than an operational issue that begins after checkout.


Taken together, these trends point towards a broader requirement.


Successful eCommerce growth increasingly depends on connecting:


Market demand → Product discovery → Search visibility → Website experience → Conversion → Delivery → Retention


Improving one component in isolation can help.


Connecting them is where the larger commercial opportunity sits.
 

Final Takeaway


Australian eCommerce continues to grow, but the nature of the opportunity has changed.


The market reached $82.6 billion in 2025, online spending continued growing into 2026 and more Australian households are purchasing online than ever before.


At the same time, average baskets are shrinking, shoppers are increasingly price-conscious, marketplace usage is rising and the path to purchase is becoming more fragmented.


Search remains central to discovery, while social platforms and AI are adding new routes through which consumers find and evaluate products.


That makes Australian eCommerce less a question of whether demand exists and more a question of which businesses are positioned to capture it.


For retailers, the opportunity sits at the intersection of market demand, visibility, digital experience, trust, fulfilment and conversion.


The businesses that understand where customers search, what influences their decisions and what prevents them from completing a purchase will be better positioned to compete for a greater share of Australia's growing online economy.